
Written by: Dr. Ahmed Al-Ahmed, Attorney at Law
Introduction
The law of agency regulates relationships in which one person (the agent) is authorized to act on behalf of and subject to the control of another person (the principal). Agency law is fundamentally principal-centered. In addition to any contractual obligations that may exist between the parties, it imposes fiduciary duties upon the agent — including duties of care and loyalty — designed to protect the principal against misuse of the authority entrusted to the agent.
The relationship is consensual: the principal manifests assent that the agent shall act on the principal’s behalf and subject to the principal’s control, while the agent consents to do so. Importantly, a formal written agreement is generally unnecessary. An agency relationship may arise expressly, impliedly, or from the parties’ course of dealing. Jenson Farms Co. v. Cargill, Inc., 309 N.W.2d 285 (Minn. 1981), illustrates how an agency relationship may arise from the practical substance of the parties’ dealings even without a formal agreement expressly establishing one.
Agency relationships are also generally terminable. Although termination in violation of a fixed-term agreement may give rise to contractual liability for damages, the underlying agency principle is that the principal ordinarily retains substantial authority over the relationship and the agent remains subject to the principal’s control.
The principal-centered character of agency law becomes particularly interesting when compared with modern corporate law. At first glance, the corporate relationship appears capable of being understood through conventional agency principles: shareholders provide the equity capital and possess the residual economic interest in the corporation; directors exercise authority over corporate affairs; and officers and managers conduct the corporation’s operations.
Yet Delaware corporate law does not simply reproduce this principal-agent model. Instead, it adopts a distinctly board-centric governance structure. Rather than treating directors as ordinary agents subject to continuing shareholder control, Delaware law vests the board itself with broad statutory authority to manage, or direct the management of, the corporation.
This represents an important departure from the traditional orientation of common-law agency doctrine. Whereas agency law begins with the authority and protection of the principal, Delaware corporate law begins with the statutory authority of the board. The resulting governance regime therefore presents an apparent paradox: directors are fiduciaries exercising authority over an enterprise in which shareholders hold the residual economic interest, yet the law deliberately insulates directors’ decision-making from direct shareholder control and substantial judicial interference.
This article examines that transition from principal-centered agency law to board-centric corporate governance. In particular, it considers how Delaware law calibrates judicial scrutiny of the two principal fiduciary concerns: challenges involving the duty of care, ordinarily considered within the deferential framework of the Business Judgment Rule, and conflicted transactions implicating the duty of loyalty, which may trigger the more exacting Entire Fairness Doctrine. It also examines the statutory protections and cleansing mechanisms through which Delaware law seeks to preserve board autonomy while maintaining fiduciary accountability.
I. Agency Law and the Primacy of the Principal
Classical agency doctrine is structured around the relationship between principal and agent. The principal delegates authority, and the agent exercises that authority on the principal’s behalf and within the scope of the agency relationship.
An essential feature of this relationship is the principal’s right of control. The agent is not merely someone whose conduct economically affects another person. Rather, the agent acts on the principal’s behalf and is subject to the principal’s control.
Agency law consequently imposes fiduciary obligations upon the agent. The agent may not exploit delegated authority for personal benefit at the expense of the principal and must comply with the duties arising from the fiduciary relationship.
Traditional agency doctrine therefore begins from a relatively clear proposition: authority originates with the principal, the agent remains subject to the principal’s control, and fiduciary law protects the principal against misuse of delegated authority.
This principal-protective orientation provides an important benchmark against which the structure of modern corporate law can be assessed.
II. The Corporation and the Emergence of Board-Centric Governance
The modern corporation introduces a substantially different allocation of authority.
Corporate governance may broadly be understood as involving three institutional levels:
- Shareholders, who contribute equity capital and hold the corporation’s residual economic interest;
- The board of directors, which exercises statutory authority over the corporation’s business and affairs; and
- Officers and management, who ordinarily conduct the corporation’s day-to-day operations under the authority and oversight of the board.
From a simplified agency perspective, one might expect shareholders, as providers of capital and residual owners, to occupy the position of principals, with directors functioning as their agents. Such an analogy is useful in explaining the economic problem created by the separation of ownership from control.
Legally, however, the analogy has important limitations.
Delaware corporate law does not treat the board as an ordinary agent required to follow the continuing instructions of shareholders. Section 141(a) of the Delaware General Corporation Law (“DGCL”) establishes the foundational allocation of corporate authority: the business and affairs of a Delaware corporation are, subject to the statute and any applicable provision in the certificate of incorporation, to be managed “by or under the direction of a board of directors.”
That statutory allocation is fundamental to understanding Delaware corporate governance. Shareholders may elect directors, vote upon certain fundamental corporate transactions, sell their shares, and invoke judicial remedies where appropriate. They generally do not, however, possess authority to direct the board regarding the corporation’s ordinary business decisions.
Thus, unlike the classical principal-agent relationship, the supposed “principal” cannot ordinarily instruct the supposed “agent” how to exercise its managerial authority.
This is the essence of the board-centric character of Delaware corporate law.
The board is therefore more than an intermediary between shareholders and management. It is a corporate organ to which the law itself allocates managerial authority. Directors owe fiduciary duties, but their authority is not merely a revocable delegation from shareholders of the kind contemplated by traditional agency doctrine.
III. The Departure from Classical Agency Doctrine
The distinction between agency law and Delaware corporate law becomes particularly apparent when the allocation of authority in the two systems is compared.
Under classical agency doctrine, the relationship can broadly be expressed as:
Principal → Delegates Authority → Agent
The agent remains subject to the principal’s control, while fiduciary doctrine protects the principal against misuse of the authority delegated to the agent.
Delaware corporate governance operates differently:
Shareholders → Elect Directors → Board Exercises Independent Statutory Authority → Management Operates Under Board Oversight
The significance of this distinction should not be understated. The board’s authority does not depend upon shareholders continuously approving its business decisions. Once elected, directors are expected to exercise their own judgment concerning the corporation’s interests rather than simply implementing shareholder instructions.
Accordingly, Delaware corporate law modifies two central features of the conventional agency relationship.
First, it substantially alters the control principle. Shareholders do not ordinarily exercise direct control over directors’ business decisions.
Second, it limits the supposed principal’s power of intervention. Although shareholders possess important governance rights, those rights are primarily structural and protective rather than managerial.
The result is an inversion — or, more precisely, a substantial modification — of the principal-centered structure encountered in classical agency doctrine. Agency law asks principally: How should the principal be protected from the agent? Delaware corporate law must answer an additional institutional question: How should directors be protected from excessive shareholder and judicial interference so that they can exercise independent business judgment?
This question lies at the heart of Delaware’s board-centric model.
Importantly, this does not mean that Delaware law abandons fiduciary accountability. Rather, it separates managerial authority from accountability. The board possesses broad authority to manage the corporation, but directors remain subject to fiduciary obligations governing the manner in which that authority is exercised.
IV. Shareholder Rights Within a Board-Centric System
Board centrality does not mean that shareholders are powerless. Rather, Delaware law gives shareholders specific mechanisms through which they may exercise influence and hold corporate fiduciaries accountable while generally withholding direct managerial authority.
These mechanisms are often summarized as the rights to vote, sell, and sue.
Shareholders exercise their voting rights primarily to elect members of the board of directors and, subject to applicable statutory and regulatory provisions, to remove them. They may also vote on certain fundamental corporate matters, including some mergers and acquisitions, amendments to the certificate of incorporation, and the sale of all or substantially all of the corporation’s assets. For example, Delaware law requires shareholder approval for the sale of all or substantially all of the corporation’s assets, pursuant to the conditions set out in §271.
Shareholders may also sell their shares and thereby exit their investment. Particularly in publicly traded corporations, the ability to exit through the market provides an important economic mechanism for responding to dissatisfaction with corporate management.
Finally, shareholders may bring direct or derivative litigation where directors or officers have violated legally recognized duties. Fiduciary litigation therefore functions as an important accountability mechanism within a governance structure that otherwise affords directors considerable decisional autonomy.
The principal fiduciary duties traditionally associated with directors are the duty of care and the duty of loyalty, together with related doctrines concerning good faith, disclosure, and corporate waste.
These shareholder rights illustrate the distinctive compromise embodied in Delaware corporate law. Shareholders possess mechanisms to select directors, exercise defined voting rights, exit their investment, and seek judicial remedies for fiduciary misconduct, but they generally do not manage the corporation themselves.
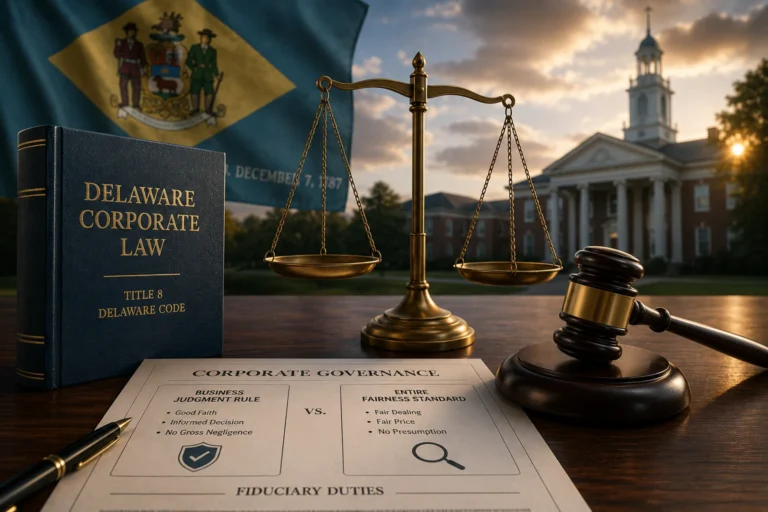
The importance of the right to sue becomes particularly apparent when the standards of judicial review are considered. Delaware law does not subject every alleged fiduciary breach to the same degree of scrutiny. Broadly speaking, ordinary board decisions challenged on care grounds receive the substantial deference associated with the Business Judgment Rule, while transactions involving disabling conflicts of interest and corresponding loyalty concerns may be subjected to the considerably more demanding Entire Fairness Doctrine judicial review.
V. The Duty of Care and the Business Judgment Rule
The board-centric nature of Delaware corporate law becomes especially apparent when examining the duty of care and the Business Judgment Rule (“BJR”).
The duty of care requires directors to act with an appropriate level of care when making decisions on behalf of the corporation. Yet Delaware courts do not ordinarily review the substantive merit of those decisions merely because shareholders allege that the board made a mistake.
Instead, the Business Judgment Rule generally protects directors from judicial second-guessing when they make informed business decisions in good faith and without disabling conflicts of interest. Courts ordinarily presume that directors acted on an informed basis, in good faith, and in the honest belief that their decisions were in the corporation’s best interests.
Thus, although the duty of care imposes a substantive fiduciary obligation upon directors, the Business Judgment Rule supplies the principal deferential framework through which ordinary business decisions challenged on care grounds are judicially reviewed.
This distinction between fiduciary duty and judicial standard of review is important. The duty of care defines the obligation owed by directors; the Business Judgment Rule determines the degree of judicial scrutiny ordinarily applied to the board’s exercise of business judgment.
The doctrine reinforces the statutory allocation of managerial authority to the board. If courts routinely reconsidered the substantive merits of directors’ business decisions, the managerial authority granted to the board under DGCL §141(a) would be substantially undermined.
The Business Judgment Rule therefore serves not merely as a rule concerning personal liability. It also performs an important institutional function: preserving the decisional autonomy of the board.
Kamin v. American Express Co., 383 N.Y.S.2d 807 (Sup. Ct. 1976), although a New York rather than Delaware decision, illustrates the broader judicial reluctance to substitute judicial judgment for legitimate business judgment. The court declined to interfere with a decision made by disinterested directors merely because shareholders considered another course of action economically preferable.
The Delaware Supreme Court’s decision in Smith v. Van Gorkom, 488 A.2d 858 (Del. 1985), demonstrates the limits of that deference. There, the court concluded that the directors had breached their duty of care by approving a merger without adequately informing themselves before acting.
The relevant standard was gross negligence, not merely an ordinary error of business judgment.
This demanding threshold reflects an important policy underlying Delaware corporate law. Directors must act with appropriate care and in good faith, but the law does not impose liability merely because a decision later proves mistaken or produces an unfavorable economic result. A regime that did so would encourage excessive risk aversion and undermine the board’s ability to exercise independent commercial judgment.
The Business Judgment Rule thus exemplifies the broader departure from classical agency doctrine: the legal system is concerned not only with protecting those whose economic interests are affected by delegated authority, but also with protecting the decision-maker’s legitimate sphere of discretion.
VI. Statutory Exculpation and DGCL §102(b)(7)
Delaware’s commitment to protecting legitimate corporate decision-making extends beyond the Business Judgment Rule.
DGCL §102(b)(7) permits a corporation, subject to statutory limitations, to include a provision in its certificate of incorporation eliminating or limiting the personal monetary liability of directors — and, under the current statute, certain officers — for specified breaches of fiduciary duty.
Historically, this provision became especially significant in relation to directors’ duty-of-care liability following Smith v. Van Gorkom. Its policy rationale is closely connected to Delaware’s board-centric governance model: imposing personal monetary liability for every failure of care could discourage qualified individuals from serving as directors and distort directors’ incentives toward excessive caution.
The statutory protection is nevertheless subject to important limits. Among other exclusions, DGCL §102(b)(7) does not permit exculpation for breaches of the duty of loyalty, acts or omissions in bad faith, willful misconduct or knowing violations of law, or transactions from which the fiduciary derives an improper personal benefit.
The statute therefore illustrates the balance inherent in Delaware’s board-centric model. Directors may receive substantial protection from personal monetary liability for certain fiduciary breaches, particularly duty-of-care claims, but board autonomy does not extend to disloyalty, bad faith, willful misconduct, or improper personal benefit.
This distinction also provides the transition to Delaware’s treatment of the second principal fiduciary obligation: the duty of loyalty. Whereas ordinary board decisions challenged on care grounds generally benefit from the deferential Business Judgment Rule, conflicted transactions implicating the duty of loyalty may trigger the considerably more demanding Entire Fairness standard.
VII. The Duty of Loyalty and the Entire Fairness Doctrine
The duty of loyalty requires directors and other corporate fiduciaries to place the interests of the corporation above their own when exercising corporate authority. It therefore becomes particularly important where a fiduciary stands on both sides of a transaction, receives a material personal benefit, or otherwise faces a disabling conflict of interest.
While alleged breaches of the duty of care ordinarily arise within the framework of the Business Judgment Rule, transactions implicating the duty of loyalty — particularly willful misconduct, self-dealing and certain controlling-stockholder transactions — may instead trigger Delaware’s more exacting Entire Fairness Doctrine.
The relationship can therefore be understood, at a general analytical level, as follows:
Duty of Care → Business Judgment Rule
Duty of Loyalty / Conflicted Transaction → Entire Fairness Doctrine
The parallel is useful, but the underlying concepts should remain distinct. The duty of care and duty of loyalty are substantive fiduciary obligations, whereas the Business Judgment Rule and Entire Fairness are standards of judicial review used by courts in determining how challenged corporate conduct should be evaluated.
Entire Fairness represents Delaware’s most rigorous standard of review. Traditionally, the analysis encompasses two interrelated components: fair dealing and fair price.
Fair dealing concerns the process surrounding the transaction, including how it was initiated, structured, negotiated, disclosed, and approved. Whereas Fair price concerns the economic and financial terms of the transaction.
The contrast with the Business Judgment Rule is significant. Under the Business Judgment Rule, courts generally defer to the board’s judgment and refrain from evaluating the substantive merits of a business decision. Under Entire Fairness Doctrine, the court undertakes a substantially more searching examination of both the process and economic substance of the challenged transaction.
This heightened scrutiny reflects the different fiduciary concern presented by loyalty cases. When directors are disinterested and independent, the law can generally presume that they are exercising judgment for the corporation. When a fiduciary possesses a material conflicting interest, however, the justification for that presumption is weakened.
Yet even here, Delaware law does not adopt an absolute rule that every conflicted transaction is prohibited or automatically gives rise to liability.
Instead, Delaware corporate law provides mechanisms through which conflicts may be addressed, including disclosure, approval by disinterested directors, approval by disinterested stockholders, and, where applicable, proof that the transaction was fair.
DGCL §144, substantially amended in 2025, now provides an extensive statutory framework governing conflicted transactions involving directors and officers as well as controlling stockholders.
With respect to transactions involving directors or officers, DGCL §144(a) generally provides statutory protection where specified requirements are satisfied, including approval by properly informed and disinterested directors acting in good faith and without gross negligence; approval or ratification by an informed and uncoerced vote of disinterested stockholders; or a showing that the transaction is fair to the corporation and its stockholders.
The statute separately addresses transactions involving controlling stockholders. Depending upon the nature of the transaction, statutory protection may arise under DGCL §144(b) through approval by an appropriately constituted committee of disinterested directors, approval or ratification by disinterested stockholders, or a showing of fairness. Going‑private transactions involving controlling stockholders are subject to more demanding statutory requirements under DGCL §144(c).
These mechanisms are significant to the broader thesis of this article. Even in the area of the duty of loyalty, where Delaware law subjects fiduciaries to its most demanding judicial scrutiny through Entire Fairness Doctrine, the law nevertheless recognizes procedures through which conflicts can be neutralized, transactions can be validated, and fiduciaries can obtain protection.
Thus, Delaware law does not treat the existence of a conflict as the end of the inquiry. Instead, it constructs a framework in which the severity of judicial review and the availability of fiduciary protection depend upon the nature of the conflict and the procedural safeguards surrounding the transaction.
This approach represents another important departure from a rigid application of classical agency principles. Traditional fiduciary doctrine begins with suspicion toward an agent’s self-interest. Delaware corporate law retains that concern but accommodates the institutional realities of corporate governance by permitting conflicted transactions to proceed where appropriate safeguards or substantive fairness justify doing so.
VIII. Why Does Delaware Protect the Board?
The extensive autonomy and protections afforded to directors raise an important policy question: Why should the law protect the board when fiduciary doctrine developed, at least in part, to protect principals from those entrusted with authority?
The answer lies in the economic and institutional function of the modern corporation.
Corporate management requires specialization, expertise, speed, continuity, and the capacity to assume commercial risk. If every significant business decision required direct shareholder approval, particularly in publicly held corporations with thousands or millions of dispersed shareholders, effective management would become impracticable.
Similarly, if directors faced personal liability whenever a commercial decision produced an unfavorable result, rational directors would have incentives to avoid risky projects even where the expected return justified the risk. Yet prudent risk-taking is an essential component of commercial enterprise.
Delaware corporate law therefore separates accountability from direct control.
Shareholders retain significant mechanisms of accountability: they elect directors, exercise voting rights over specified fundamental matters, may exit by selling their shares, and may invoke judicial remedies when fiduciary obligations are violated.
At the same time, directors receive considerable autonomy to manage the corporation without continuous shareholder direction or routine judicial supervision.
This allocation of authority explains why Delaware corporate law is appropriately characterized as board-centric rather than shareholder-managerial. Shareholders possess important governance rights, but the legal system does not generally place the management of the corporate enterprise directly in their hands.
The two principal fiduciary regimes discussed above further illustrate this calibrated approach.
In the context of the duty of care, Delaware begins from substantial deference through the Business Judgment Rule and supplements that protection through statutory exculpation under DGCL §102(b)(7).
In the context of the duty of loyalty, Delaware responds to conflicts with the heightened scrutiny of Entire Fairness Doctrine where applicable, while nevertheless recognizing statutory and procedural mechanisms through which appropriately structured conflicted transactions may receive protection.
These doctrines differ in their intensity, but they reflect the same underlying institutional objective: the board must remain accountable, yet it must also possess sufficient independence and legal protection to govern effectively.
Conclusion: From Principal-Centered Agency to Board-Centric Corporate Law
The comparison between agency law and Delaware corporate law reveals an important evolution in the legal treatment of delegated authority.
Classical agency doctrine begins with the principal. Authority is delegated by the principal to an agent who acts on the principal’s behalf and remains subject to the principal’s control, while fiduciary obligations protect the principal against misuse of that authority.
Delaware corporate law begins from a materially different institutional premise. Under DGCL §141(a), managerial authority is vested in the board of directors. Shareholders elect directors and retain important voting, exit, and litigation rights, but they do not ordinarily exercise direct managerial control over the board.
In this respect, Delaware corporate law is fundamentally board-centric, and that board-centric structure represents a significant departure from the principal-centered orientation of traditional common-law agency doctrine.
The treatment of fiduciary duties further illustrates this departure. In the context of the duty of care, the Business Judgment Rule provides directors with substantial judicial deference, while DGCL §102(b)(7) permits additional protection from personal monetary liability for specified fiduciary breaches. In the context of the duty of loyalty, conflicted transactions may trigger the more exacting Entire Fairness Doctrine but Delaware nevertheless recognizes mechanisms — including independent approval, stockholder approval, and fairness-based protections — through which conflicts may be addressed without automatically invalidating the transaction or imposing liability.
The apparent tension between agency law and corporate law is therefore not necessarily an inconsistency. Rather, it reflects the different institutional objectives served by the two bodies of law.
Agency doctrine is principally concerned with regulating a fiduciary entrusted with authority to act on another’s behalf. Corporate law must address that concern while simultaneously enabling a board to manage a complex economic enterprise independently, efficiently, and with an appropriate willingness to assume commercial risk.
The resulting model represents a deliberate legal compromise: shareholders are protected through fiduciary duties and defined governance rights, while directors are protected through statutory authority, board autonomy, judicial deference, and carefully calibrated standards of review and limitations on personal liability.
Thus, the evolution from common-law agency principles to Delaware corporate governance may be understood as a movement from principal protection toward board-centric fiduciary governance — a system in which accountability remains essential, but managerial authority is deliberately concentrated in the board rather than in the shareholders whose capital ultimately supports the enterprise.